Author: B&T Advisory

Staff Profile: Maddie Robinson

Can you share a bit about your background? How did you come to work with the team at B&T Advisory?

My career began in aged care, where I completed medical training and gained pre-nursing certification. I then moved into aged care and disability, eventually progressing into the NDIS sector, where I worked for several years, including throughout COVID.

In 2021, I took a break from the NDIS and moved into real estate sales and finance brokerage. That’s where I got into the corporate side of things. When I started, there were only four staff, and there weren’t really any processes in place, so I ended up writing many of the business’s processes and taking on more and more. Eventually I was like, “I can’t do all this by myself,” so I started hiring people. By the time I left, the business had around 20 people.

I eventually returned to the disability sector, first as a Support Worker and then progressing to Participant Support Officer and Support Coordinator. I later moved into the therapy sector, working alongside Occupational Therapists and Speech Pathologists.

One thing to know about me is that I am always up for a challenge and always keen to learn. When I came across the role at B&T Advisory, it really caught my eye because I’d never worked in this area before.
I thought, “I want to learn how that works.”

You’ve worked across some very different industries. What have you brought from those experiences into your role at B&T Advisory?

I think business connections are the same across industries. Knowing how to communicate, relay information, and ensure what you provide is accurate, relevant, and compliant with legislation. No matter what industry I’ve been in, legislation has always been a part of it. In the NDIS, we had certain guidelines we had to follow, and in liquidation, everything needs to be done to the T. There are lots of things that are very new to me, and I’m getting up to speed fast. But things like meetings, documents, preparation, and following legislation are very much the same.

What professional achievement are you most proud of?

One of my biggest achievements was helping transform the real estate sales and finance brokerage business that I mentioned earlier. When I started, there weren’t really any processes, and there were only a handful of staff. Being part of that growth and seeing how the changes I helped introduce made a real difference to the business was incredibly rewarding.
I was also fortunate enough to receive an award in recognition of my contribution, which was one of the most heartwarming moments of my career.
The award wasn’t just about recognition. It was knowing that the work I had put in had genuinely made a difference and helped the business move forward.

What’s the most rewarding aspect of the work you do?

One of the things I value most is being able to support the team by sharing ideas and suggestions that improve the way we work.
I enjoy looking at processes from a different perspective and finding ways to make tasks more effective and streamlined. Seeing those suggestions help the team work more efficiently and achieve stronger outcomes is very rewarding.

What have you learned from your colleagues that’s made you better at your job?

Everything I learn about this industry from my colleagues helps me do my job better. Understanding their roles, responsibilities, and the processes they manage helps me better appreciate how each person contributes to supporting our clients. The more I learn about what they do, the better I can support the team and understand how we work together to achieve the best outcomes for our clients.

What are you hoping to achieve in your role at B&T Advisory?

I want to help drive business growth, but also people’s growth. Whether it’s systems, actions, or tasks, I want everything to run smoothly. I want people to be able to show up and just know exactly what they need to do and how. I’m working with Neil on that now, and I’m excited about it.

What book or podcast has influenced you most recently?

One podcast I’ve followed since 2022 is The Diary of a CEO with Steven Bartlett. I enjoy hearing from different business owners and people in different positions and learning how they see the world, approach challenges, and think about success. The podcast also explores everyday life, mindset and different perspectives, which often challenges me to think more broadly about both work and life. I highly recommend it to anyone who enjoys learning, challenging their perspective and looking at things from a different point of view.

CONTACT US

Continue reading

Small Business Restructuring

Why we are seeing SBR success rates improving

By Travis Pullen, Director

Small Business Restructuring (SBR) is seeing renewed support, with success rates improving and the process becoming more consistent for practitioners and their clients.

For many businesses, SBR remains a great way to restructure and survive longer term. But proposal quality matters, and expecting a 15-cent-in-the-dollar dividend over three years is no longer the norm.

Businesses now need to come forward with better-quality proposals. At the same time, practitioners are getting better at identifying which businesses are likely to be suitable candidates before they enter the process.

Together with better and more consistent feedback from the Australian Taxation Office (ATO), this appears to be contributing to better outcomes.

Better proposals and better feedback

At a recent conference I attended in Canberra, representatives from the ATO’s small business restructure team acknowledged that the quality of practitioner reporting and the detail of information being provided had improved.

That matters because better information gives the ATO more to work with when assessing a proposed restructure. But the improvement isn’t only coming from practitioners.

Towards the end of last year, we felt the quality of feedback we received from the ATO on draft reports could sometimes be inconsistent. That’s changed.

We’re finding the feedback on draft proposals is giving us a clearer indication of where a proposal may need to land. This lets us go back to the client and their accountant with more confidence and say, “Look, if you get this up to 30 cents in the dollar over six months,” for example, “we think you’ve got a good shot at this.”

We now are seeing that the current average dividend across all SBRs that B&T Advisory has done is 30 cents per dollar.

Historically, our approval rates are around 80%. Since February, it has been 100%.


ATO Support against Appointments FYE 2025-26
Source: 2026 AIIP Conference Slide Pack

Why the draft process matters

Providing the ATO with a draft report isn’t new. For a long time, the ATO has encouraged practitioners to use the process. It does require everyone to work together.

The ATO requests at least one clear week before the final due date to review the draft and provide feedback. We then need enough time to go back to the client, make any necessary changes and get the final report out. But the statistics show that when the ATO has had a chance to review a draft and provide feedback, those SBRs are noticeably more successful than when they haven’t.

I was surprised to learn recently that some firms don’t bother with draft reports or seek feedback, including firms doing a large volume of SBRs.

Correlation doesn’t always mean causation, of course, but when the option is there, and you look at the numbers, it’s a worthwhile part of the process. Accountants are often key to making that process work. If they’re willing to work with their clients and with us to get the information through early, it gives us more time to prepare the report and start talking to the ATO.


Draft Plan Review by ATO
Source: 2026 AIIP Conference Slide Pack

What does a good SBR candidate look like now?

At its heart, a good SBR candidate is a good underlying business. It may be that a past issue is what’s led to the tax debt. The business may have done something wrong internally with its processes or made a bad business decision.

We encourage directors to be completely honest in their statements about why they believe the tax debt occurred and why they haven’t been able to pay it. But if the underlying business is solid, shedding 70 or 80 per cent of that tax debt can be the difference between a viable, thriving business going forward and one that has to close down.

There are also red flags to consider.

Two of the big ones are compliance history and director loans. The ATO wants to see that the business has made an effort with its lodgements and has made at least some attempt to pay tax. They will also look at whether the director has been taking money themselves rather than paying the company’s debts. If a business can show it’s making an honest go, then in my view an SBR is much more likely to be successful.

The earlier a business seeks advice, the better

For accountants and other trusted advisors, one key message remains: the earlier a business comes to us, the better. There are a lot of options available. It might be an SBR. It might be some form of restructure and sale of the business. It might be negotiating a payment plan with the ATO or other creditors.

Getting advice early gives the business the opportunity to assess its position and work out which option is most likely to help it move forward.

What happens after a successful SBR?

One question we don’t yet have a clear answer to is what happens to businesses several years after completing an SBR.

It’s something we’ve thought about in the office. Once we hand the company back, so to speak, it goes on its merry way. Sometimes we find out that a business completed a successful SBR and then went into liquidation a year later. It does happen. But it’s still a bit early to know how many businesses this represents.

Over the next couple of years, there should be enough time and enough matters to conduct some studies into what happens to businesses longer term.

A viable option for the right business

Overall, the ATO is supporting SBRs, but expectations have changed. Average dividend payouts are higher. The quality of proposals has improved. ATO feedback has become more consistent, and practitioners have a clearer picture of which businesses are likely to get through the process successfully.

For a business with a solid underlying operation and a legacy tax debt, SBR still remains a genuine option. The key is to get advice early, provide quality information, and put forward the right proposal.

Source: Coffee Commune September 2026  The Small Business
Restructuring Landscape, Peter Biazos 

CONTACT US

Continue reading

Sharing New Perspectives Conference

Peter and Travis recently spent time in Bali joining our friends at Helm Advisory, GM Advisory, and Insolve for their Litigation & Insolvency Conference.

Now in its fifth year, the conference brought together leading lawyers, insolvency practitioners, academics, and industry specialists to share perspectives and learnings through a series of panels, presentations, and case studies. 

Held over three days, the conference saw both Peter and Travis take part in several panels, sharing their deep experience and insights.

It was also a great opportunity to spend time with others across the insolvency and legal community, compare experiences and tackle some of the profession’s challenges together.

  • Peter Panel 1

  • Peter Panel 2

  • Peter Panel 3

  • Travis Panel 1

  • Travis Panel 2

  • Travis Panel 3

  • Travis Panel 4

  • Bali 2

  • Bali 1

CONTACT US

Continue reading

Staff Profile: Jessica Barnes

What inspired you to pursue a career in insolvency?

I actually wanted to get into insolvency! A lot of people are surprised and say, “Oh, really?” because everyone else just kind of falls into it.

When I was in high school, my dad worked for a company that went into voluntary administration. He gave me the reports to read. I just found the process so interesting.

I think it was probably around the time when I was making career choices and picking subjects, and I just thought, that’s what I want to do. So, after I finished my accounting degree, I looked for an insolvency graduate job, and my career went from there.

So you’ve only ever worked in insolvency?

Yes. I’ve worked for two firms previously. I was at the first firm for 11 years, then at the second for a few years before COVID, and then I took a career break to raise my children. In both firms, I worked on corporate and personal insolvency matters.

How did you come to be working at B&T?

I’ve got three young kids, and recently I decided I wanted to get back into part-time work. I told my husband my plan, and that exact same day, a recruiter messaged me on LinkedIn and said, “If you’re looking for anything, let me know.”

I rang him and said, “Excellent timing. Yes, I am.”

He told me about a great opportunity at B&T Advisory, and I’ve been here for just over a month.

How have you found the transition back to work?

It’s nice having a different challenge from home life.

I’m working remotely, so there’s the challenge of being my own company all day, but I’m enjoying it so far.

What does your role at B&T involve?

I’m working with Neil as part of his team.

At the moment, I’m working on a few existing files and supporting the team on matters as they come up.

What personal or professional achievement are you most proud of?

Professionally, I would probably say getting my qualifications as a chartered accountant.

Personally, it’s my kids… obviously!

What is the most rewarding aspect of the work you do?

Insolvency can be an emotional process for everyone involved, but I think it’s just being the person who can guide people in a professional and reassuring way.

What have you learned from colleagues that has made you better at your job?

I’ve worked with some great people, and I think you draw inspiration from each of them by watching how they operate and what you like or don’t like.

A couple of things have really stood out for me.

One of the first practitioners I worked for as a graduate said, “Have a go, because pretty much anything can be fixed if you make a mistake. So, don’t be afraid.”

Another practitioner always said to the team, “Never burn a bridge,” because you never know when you’ll see that person again or if you might need something.

I think they’re the two standouts.

Is there a book or podcast that has influenced you recently?

I wish I had time!

I don’t even remember the last book that I read. I’ve got books sitting on my bedside table now. One day. One day.

What would you like people to know about you as part of the B&T team?

I’m excited to work with the team at B&T Advisory. One of the things that was important to me when getting back into insolvency was working in small teams and working closely with people.

I’m a very shy person, so part of me feels like, “Don’t write anything about me,” but here we are!

They’ve been really welcoming, so I’m loving my time here.

CONTACT US

Continue reading

Less Equity, Tighter Lending

The Flow-On Effect for Business Owners

By Peter Biazos, Managing Director

Australia’s property market appears to be slowing, and falling property prices don’t just affect homeowners and investors.

For business owners who have traditionally relied on equity in their home or investment properties to support their businesses, this could have a flow-on effect.

Less equity means fewer people can borrow, reborrow or redraw into their account.

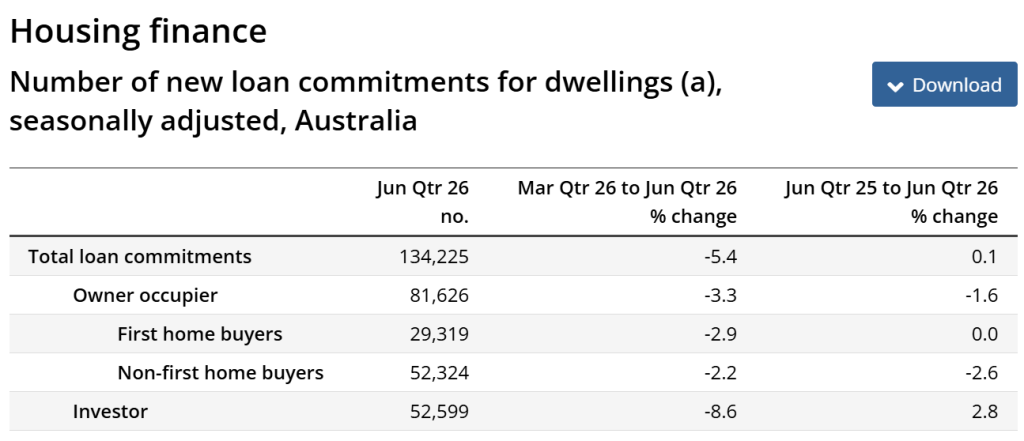
At the same time, interest rates are higher, so people’s borrowing capacity is already down. Loan applications are down, and approvals are down.

Source: https://www.abs.gov.au/statistics/economy/finance/lending-indicators/latest-release

Additionally, properties are staying on the market longer before they sell, and new stock isn’t necessarily coming onto the market either.

It seems that everything is grinding to a halt.

When the equity isn’t there anymore

For businesses experiencing cash flow pressure and carrying debt, access to equity has kept things going. They may have used money out of their own cash reserves or tried to access equity from their property. That’s getting harder now and losing access to that equity creates a problem.

And the problem is twofold. You have people who have only their matrimonial home, and you have people who own investment properties. If their mortgage repayments are going up and they see their property value coming down, the current market makes it hard to sell and unlock that equity. Rent prices will keep increasing which will also have a flow on effect on disposable income.

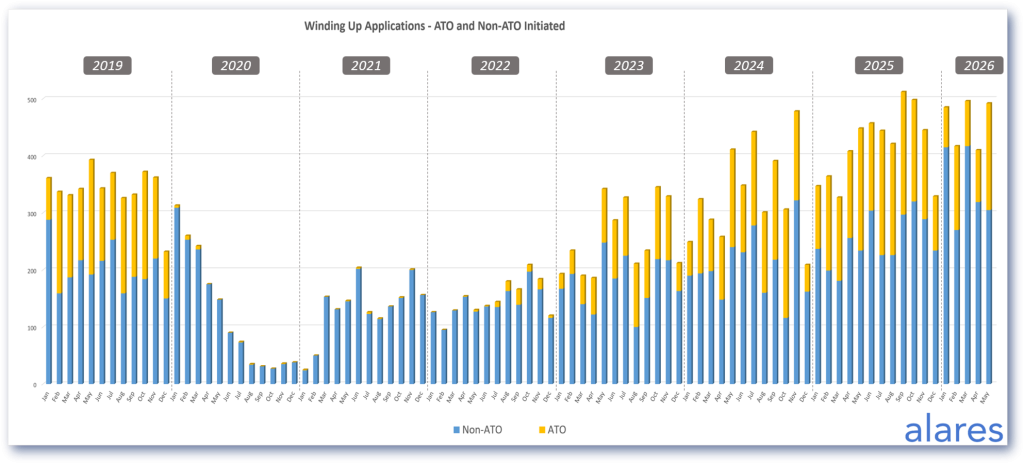
At the same time, creditor activity is increasing, and we’re seeing the ATO issuing a high number Director Penalty Notices and taking action against businesses.

Winding-up applications 2019 – 2026

Source: https://alares.com.au/insights/01-06-2026 

The risk of negative equity

There’s also the issue of negative equity for people who bought property with a small deposit.

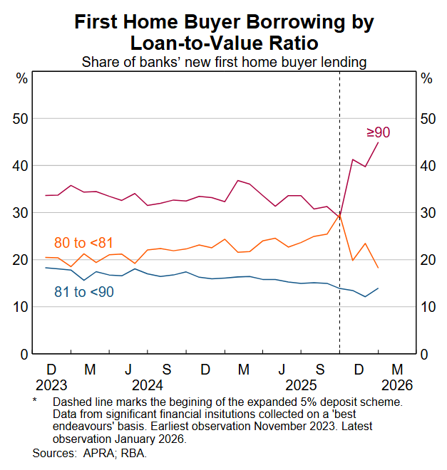
With the 5% deposit scheme, unit prices under a million dollars suddenly started going up. Demand was going through the roof.

The RBA data below shows that the share of first home buyers borrowing at LVRs of 90% or more increased sharply after the Australian Government expanded the 5% Deposit Scheme in October 2025.

Now, if property prices continue to fall, we could see another potential flow-on effect: people who got into the market with a 5% deposit could end up in negative equity.

Source: 2. Resilience of Australian Households and Businesses | Financial Stability Review – March 2026 | RBA

It may take some time to filter through

From an insolvency perspective, we don’t anticipate a significant impact in the short term. It needs to filter into the economy a little bit more.

The impact is likely to become clearer as home owners start applying for loans and realise they’re getting knocked back or can only borrow less than they could a few months ago.

That will affect their ability to keep trading their business without that cash, and the question then becomes: can the company keep trading?

That’s where getting advice sooner rather than later becomes important.

Struggling business owners shouldn’t sit on their hands. They need to be proactive and seek advice from an insolvency practitioner or a trusted advisor.

What should accountants and lawyers be looking out for?

If a client comes to their accountant or lawyer and says, “I’m in a bit of strife and need to release some cash,” it’s time to consider their options.

Don’t necessarily rely on the big four banks.

There are other lenders out there who can assist. Obviously, we’re not talking about lenders of last resort, but second-tier lenders with slightly higher interest rates that may look at a borrower more favourably than a bank.

We’re also seeing more people relying on private lending.

You’ve got to be aware of the risk in going to lenders of last resort. If you’re seeing interest rates at 4% per month or equivalent, don’t jump in and sign up. Be wary of large establishment fees and the like.

We know that desperate situations can make people do things they probably would never have dreamed of doing.

People seem to be paralysed

Interestingly, we have seen a bit of a downturn in insolvency work in recent times which is due to various factors.  That said, in recent weeks the enquiry and conversion rates have increased but I would call things “patchy”.

Maybe things are so bad that everyone’s a little bit paralysed.  

For business owners facing these pressures, it’s about making the decisions you can with the information and data in front of you, and relying on a group of trusted advisers for that advice.

It’s not burying your head in the sand. It’s: “Okay, yep, this is a bumpy time. Let’s get all of the people in our corner to help us through.”

If you’ve got a client who is experiencing cash flow difficulties, you can reach out to us for a confidential discussion.

CONTACT US

Continue reading