Small Business Restructuring

Why we are seeing SBR success rates improving

By Travis Pullen, Director

Small Business Restructuring (SBR) is seeing renewed support, with success rates improving and the process becoming more consistent for practitioners and their clients.

For many businesses, SBR remains a great way to restructure and survive longer term. But proposal quality matters, and expecting a 15-cent-in-the-dollar dividend over three years is no longer the norm.

Businesses now need to come forward with better-quality proposals. At the same time, practitioners are getting better at identifying which businesses are likely to be suitable candidates before they enter the process.

Together with better and more consistent feedback from the Australian Taxation Office (ATO), this appears to be contributing to better outcomes.

Better proposals and better feedback

At a recent conference I attended in Canberra, representatives from the ATO’s small business restructure team acknowledged that the quality of practitioner reporting and the detail of information being provided had improved.

That matters because better information gives the ATO more to work with when assessing a proposed restructure. But the improvement isn’t only coming from practitioners.

Towards the end of last year, we felt the quality of feedback we received from the ATO on draft reports could sometimes be inconsistent. That’s changed.

We’re finding the feedback on draft proposals is giving us a clearer indication of where a proposal may need to land. This lets us go back to the client and their accountant with more confidence and say, “Look, if you get this up to 30 cents in the dollar over six months,” for example, “we think you’ve got a good shot at this.”

We now are seeing that the current average dividend across all SBRs that B&T Advisory has done is 30 cents per dollar.

Historically, our approval rates are around 80%. Since February, it has been 100%.


ATO Support against Appointments FYE 2025-26
Source: 2026 AIIP Conference Slide Pack

Why the draft process matters

Providing the ATO with a draft report isn’t new. For a long time, the ATO has encouraged practitioners to use the process. It does require everyone to work together.

The ATO requests at least one clear week before the final due date to review the draft and provide feedback. We then need enough time to go back to the client, make any necessary changes and get the final report out. But the statistics show that when the ATO has had a chance to review a draft and provide feedback, those SBRs are noticeably more successful than when they haven’t.

I was surprised to learn recently that some firms don’t bother with draft reports or seek feedback, including firms doing a large volume of SBRs.

Correlation doesn’t always mean causation, of course, but when the option is there, and you look at the numbers, it’s a worthwhile part of the process. Accountants are often key to making that process work. If they’re willing to work with their clients and with us to get the information through early, it gives us more time to prepare the report and start talking to the ATO.


Draft Plan Review by ATO
Source: 2026 AIIP Conference Slide Pack

What does a good SBR candidate look like now?

At its heart, a good SBR candidate is a good underlying business. It may be that a past issue is what’s led to the tax debt. The business may have done something wrong internally with its processes or made a bad business decision.

We encourage directors to be completely honest in their statements about why they believe the tax debt occurred and why they haven’t been able to pay it. But if the underlying business is solid, shedding 70 or 80 per cent of that tax debt can be the difference between a viable, thriving business going forward and one that has to close down.

There are also red flags to consider.

Two of the big ones are compliance history and director loans. The ATO wants to see that the business has made an effort with its lodgements and has made at least some attempt to pay tax. They will also look at whether the director has been taking money themselves rather than paying the company’s debts. If a business can show it’s making an honest go, then in my view an SBR is much more likely to be successful.

The earlier a business seeks advice, the better

For accountants and other trusted advisors, one key message remains: the earlier a business comes to us, the better. There are a lot of options available. It might be an SBR. It might be some form of restructure and sale of the business. It might be negotiating a payment plan with the ATO or other creditors.

Getting advice early gives the business the opportunity to assess its position and work out which option is most likely to help it move forward.

What happens after a successful SBR?

One question we don’t yet have a clear answer to is what happens to businesses several years after completing an SBR.

It’s something we’ve thought about in the office. Once we hand the company back, so to speak, it goes on its merry way. Sometimes we find out that a business completed a successful SBR and then went into liquidation a year later. It does happen. But it’s still a bit early to know how many businesses this represents.

Over the next couple of years, there should be enough time and enough matters to conduct some studies into what happens to businesses longer term.

A viable option for the right business

Overall, the ATO is supporting SBRs, but expectations have changed. Average dividend payouts are higher. The quality of proposals has improved. ATO feedback has become more consistent, and practitioners have a clearer picture of which businesses are likely to get through the process successfully.

For a business with a solid underlying operation and a legacy tax debt, SBR still remains a genuine option. The key is to get advice early, provide quality information, and put forward the right proposal.

Source: Coffee Commune September 2026  The Small Business
Restructuring Landscape, Peter Biazos 
CONTACT US

Continue reading

Less Equity, Tighter Lending

The Flow-On Effect for Business Owners

By Peter Biazos, Managing Director

Australia’s property market appears to be slowing, and falling property prices don’t just affect homeowners and investors.

For business owners who have traditionally relied on equity in their home or investment properties to support their businesses, this could have a flow-on effect.

Less equity means fewer people can borrow, reborrow or redraw into their account.

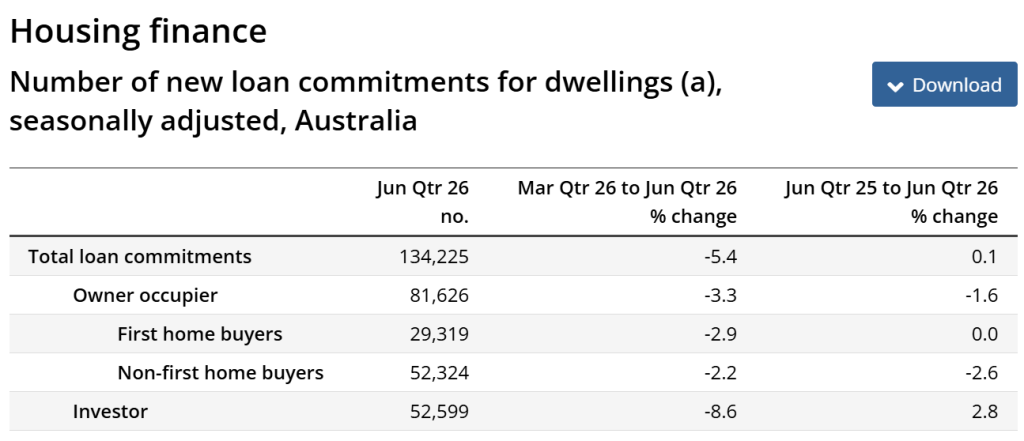
At the same time, interest rates are higher, so people’s borrowing capacity is already down. Loan applications are down, and approvals are down.

Source: https://www.abs.gov.au/statistics/economy/finance/lending-indicators/latest-release

Additionally, properties are staying on the market longer before they sell, and new stock isn’t necessarily coming onto the market either.

It seems that everything is grinding to a halt.

When the equity isn’t there anymore

For businesses experiencing cash flow pressure and carrying debt, access to equity has kept things going. They may have used money out of their own cash reserves or tried to access equity from their property. That’s getting harder now and losing access to that equity creates a problem.

And the problem is twofold. You have people who have only their matrimonial home, and you have people who own investment properties. If their mortgage repayments are going up and they see their property value coming down, the current market makes it hard to sell and unlock that equity. Rent prices will keep increasing which will also have a flow on effect on disposable income.

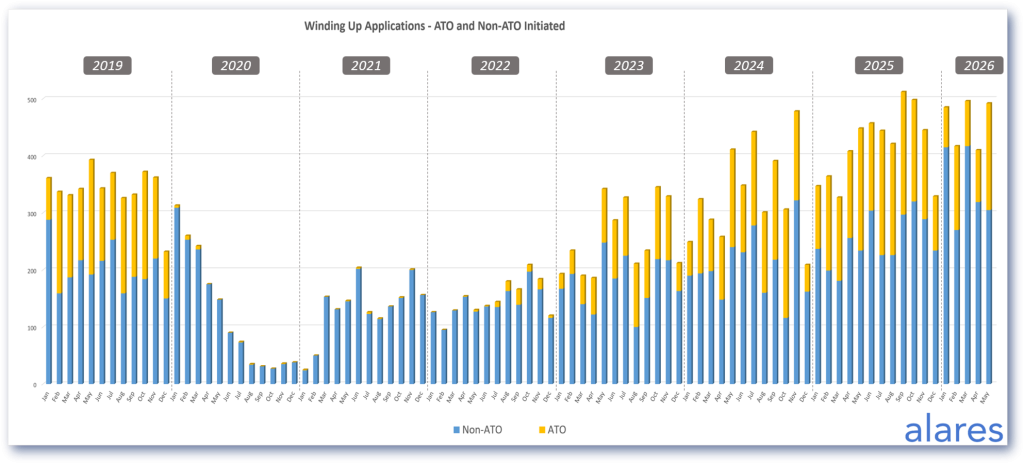
At the same time, creditor activity is increasing, and we’re seeing the ATO issuing a high number Director Penalty Notices and taking action against businesses.

Winding-up applications 2019 – 2026

Source: https://alares.com.au/insights/01-06-2026 

The risk of negative equity

There’s also the issue of negative equity for people who bought property with a small deposit.

With the 5% deposit scheme, unit prices under a million dollars suddenly started going up. Demand was going through the roof.

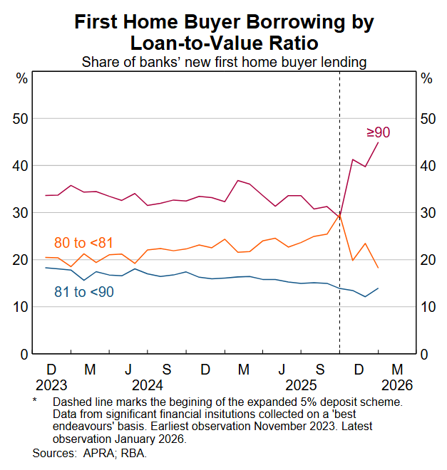
The RBA data below shows that the share of first home buyers borrowing at LVRs of 90% or more increased sharply after the Australian Government expanded the 5% Deposit Scheme in October 2025.

Now, if property prices continue to fall, we could see another potential flow-on effect: people who got into the market with a 5% deposit could end up in negative equity.

Source: 2. Resilience of Australian Households and Businesses | Financial Stability Review – March 2026 | RBA

It may take some time to filter through

From an insolvency perspective, we don’t anticipate a significant impact in the short term. It needs to filter into the economy a little bit more.

The impact is likely to become clearer as home owners start applying for loans and realise they’re getting knocked back or can only borrow less than they could a few months ago.

That will affect their ability to keep trading their business without that cash, and the question then becomes: can the company keep trading?

That’s where getting advice sooner rather than later becomes important.

Struggling business owners shouldn’t sit on their hands. They need to be proactive and seek advice from an insolvency practitioner or a trusted advisor.

What should accountants and lawyers be looking out for?

If a client comes to their accountant or lawyer and says, “I’m in a bit of strife and need to release some cash,” it’s time to consider their options.

Don’t necessarily rely on the big four banks.

There are other lenders out there who can assist. Obviously, we’re not talking about lenders of last resort, but second-tier lenders with slightly higher interest rates that may look at a borrower more favourably than a bank.

We’re also seeing more people relying on private lending.

You’ve got to be aware of the risk in going to lenders of last resort. If you’re seeing interest rates at 4% per month or equivalent, don’t jump in and sign up. Be wary of large establishment fees and the like.

We know that desperate situations can make people do things they probably would never have dreamed of doing.

People seem to be paralysed

Interestingly, we have seen a bit of a downturn in insolvency work in recent times which is due to various factors.  That said, in recent weeks the enquiry and conversion rates have increased but I would call things “patchy”.

Maybe things are so bad that everyone’s a little bit paralysed.  

For business owners facing these pressures, it’s about making the decisions you can with the information and data in front of you, and relying on a group of trusted advisers for that advice.

It’s not burying your head in the sand. It’s: “Okay, yep, this is a bumpy time. Let’s get all of the people in our corner to help us through.”

If you’ve got a client who is experiencing cash flow difficulties, you can reach out to us for a confidential discussion.

CONTACT US

Continue reading

Turning a Potential Business Liquidation into a Successful VA

By Troy Graham, Senior Manager, Sydney Office

A profitable teaching college specialising in the food and hospitality industry was facing liquidation after accumulating a significant debt to its landlord.

B&T Advisory was approached by the company’s external accountant because, like many businesses, it had been heavily impacted during COVID. As a large proportion of its students were international, closed borders and restrictions on student intake meant that while the business did not necessarily suffer immediately, the follow-on effect of closed international borders affected the business post-COVID.

Because the college runs two- or three-year courses, the true impact did not end when COVID restrictions lifted – two years without new student intake continued to affect the business for years afterwards.

Looking beyond liquidation

When the accountant first approached our Sydney team, the initial thought was to place the company into liquidation. However, after reviewing the circumstances (a profitable business with a strong outlook), we questioned whether liquidation was the right outcome and suggested considering a voluntary administration option.

Keeping the business operating

The appointment of a Voluntary Administration occurred in the middle of a teaching term, so simply shutting the business was an unfavourable option.

Our team continued trading the business throughout the voluntary administration, keeping employees working while ensuring students could continue attending classes without disruption.

For six weeks, the business continued to operate while the team coordinated all the moving pieces.

A better outcome for everyone

The company ultimately entered into a Deed of Company Arrangement, satisfied its deed obligations, and creditors received their forecast distribution.

Today, the business remains profitable.

The outcome meant:

  • Employees kept their jobs.
  • Students remained in college with no disruption to their studies.
  • Creditors received their forecast distribution.
  • The business continued trading from new premises.

Why this matter was different

What made this matter unique was that there was really only one creditor who’s debt was unserviceable.

That creditor couldn’t simply compromise the debt through a commercial agreement, so the business was required to go through a formal insolvency process.

Ideally, if the director had been able to negotiate directly with the creditor, the process would have been much easier. The director had tried to do this, and ultimately the voluntary administration facilitated what the Director had been trying to achieve himself.

Working together to achieve a better outcome

The referring accountant played an important role throughout the process.

To put the Deed of Company Arrangement in place, the accountant worked with the director to obtain finance and bring the company’s financial records up to date.

Because the accountant had been involved with the business prior to our appointment, they had a detailed understanding of the financial position, whereas the director was naturally more focused on day-to-day operations.

Working together meant the company was able to continue trading, the accountant retained their client and continued supporting the business, and together we achieved a better outcome than a liquidation.

The importance of seeking advice early

One of the biggest lessons from this matter is that there isn’t always just one outcome.

Even if it doesn’t result in an appointment with B&T Advisory, it’s worth running ideas by an advisor to obtain a second opinion.

Commonly, there is one piece of the puzzle that seems insignificant to the referrer/director; however, such a fact can completely change the outcome.

Seeking advice early, sounding out the issues and keeping an open mind about the best outcome for the client can make all the difference.

Every little detail, even if it doesn’t seem important at the time, could be the game changer!

CONTACT US

Continue reading

New Anti-Money Laundering Laws are now in Effect

By Peter Biazos, Managing Director

The AUSTRAC “Tranche 2” reforms for anti-money laundering and counter-terrorism financing (AML/CTF) under the Anti-Money Laundering and Counter-Terrorism Financing Act 2006 (Cth) (AML/CTF), which went into effect on 1 July 2026, will bring many legal, accounting and insolvency practices into the regulatory framework for the first time.

In this article, our Managing Director, Peter Biazos, examines these new compliance obligations and their implications for trusted Advisors.

Background

This is a national change and will apply to designated services commonly provided by:

  • Legal practitioners – property conveyancing, client account operations, company establishment, and trust-related services.
  • Accountants – handling client funds, supporting the planning or execution of financial transactions, and creating companies or trusts.
  • Conveyancers – facilitating the acquisition, sale, or transfer of real property.
  • Real estate agents and brokers – arranging or brokering real estate transactions.
  • Dealers in precious metals and stones – conducting high-value purchases, sales, or exchanges of precious items.

The expansion aligns Australia with international standards and imposes requirements on ‘tranche 2 entities’ similar to those already established in countries like the United Kingdom.

Classified as a reporting entity and supervised by AUSTRAC, the Commonwealth financial intelligence regulator, these practitioners are now required to meet anti-money laundering obligations whenever they provide a “designated service” as outlined above.

The primary objective of these obligations is to ensure that practitioners are alert to red flags that may indicate money laundering or terrorist financing and promptly report these concerns to AUSTRAC.

Activity-based, not profession-based

Importantly, the obligations related to Anti-Money Laundering (AML) and Counter-Terrorism Financing (CTF) are activity-based rather than profession-based. This means that AML/CTF obligations arise when a practitioner begins providing a designated service.

This also means that B&T Advisory will become a reporting entity, particularly in instances where we are required to:

  • begin managing or carrying out a sale of assets
  • participate in, or act for a person in, a financing or restructuring transaction
  • take control of and manage funds as part of a transaction (such as receiving, holding and controlling sale proceeds)
  • trade on a business and make payments or handle funds as part of that activity.

Source: How designated services apply to insolvency practitioners | AUSTRAC

Core Obligations

Under the reforms, a Reporting Entity is required to:

  • Enrol with AUSTRAC by July 29, 2026
  • Assess the money laundering and terrorism financing risks that their services could be exposed to.
  • Develop and implement a documented AML/CTF framework setting out internal policies, procedures, and controls to identify, manage, and reduce those risks
  • Implement customer due diligence measures, including identity verification, enhanced checks for higher-risk clients, and ongoing transaction monitoring.
  • Appoint a management-level AML/CTF compliance officer, who will be responsible for training staff to recognise red flags and know what to do when they see them.
  • Keep records for 7 years by setting up a record-keeping system that enables storage and simple retrieval of the right records.
  • Submit mandatory reports to AUSTRAC through its online portal, including suspicious matter reports and reports for cash transactions of $10,000 or more.

Source: Your obligations | AUSTRAC

Key Red Flags

The suspicious matters that practitioners should be aware of are warning signs of potential money laundering or terrorism financing that may require investigation. These include:

  • Unusual payment methods
  • Sources of wealth that are unclear or cannot be readily explained
  • Unnecessarily complex ownership structures
  • Limited face-to-face interaction with clients who seek anonymity or are reluctant to provide requested information
  • Rushed or overly urgent instructions that often accompany transactions that lack a clear legal or commercial purpose.
  • A rapid change of advisors without a clear reason.

Source: Risk insights and indicators of suspicious activity for accountants | AUSTRAC

A Suspicious Matter Report (SMR) must be lodged when you have reasonable grounds to suspect that a customer or transaction is linked to criminal activity. Standard timing for submission is:

  • 24 hours of forming the suspicion if related to terrorism financing
  • 3 business days for other suspicions.

Source: Suspicious matter reports | AUSTRAC

What Are the Penalties for Non-Compliance?

AUSTRAC has extensive enforcement powers. Corporations found in serious breach of these laws may face civil penalties of up to AUD 22.2 million per contravention, while individuals may be fined up to AUD 4.4 million. For the most severe violations, criminal penalties, including imprisonment, can apply.

While AUSTRAC typically works collaboratively with businesses to encourage compliance, it has shown that it will impose substantial penalties on those who repeatedly or intentionally fail to comply.

What do these changes mean for our Referrers and Clients?

For AML/CTF purposes, the client is the person or entity being assisted through the designated service, not necessarily the person who appointed the practitioner.

Customer Due Diligence is a core tenet of the obligations. It requires Practitioners to establish who the client is, whether the client is a company, trust, or another structure, and to identify the individuals who control it.

This will require further layers of identity verification, including requests for passports and drivers’ licences, as well as more detailed questioning about the ownership and control of companies.

These requests are legal requirements, and all information collected will be handled in accordance with our privacy policy and only used for the purposes required by law.

For our existing clients and referrers, these checks only apply when you next engage us for a new appointment.

Looking Ahead

This overview article is intended as a starting point only.

Australia’s Tranche 2 AML/CTF reforms are broad, and many practical questions will continue to be worked through as firms implement new processes and regulators provide more guidance.

There is considerably more to discuss than can be covered in one article. For lawyers and accountants, the key task at this stage is to identify which activities within their practices may constitute designated services and to begin preparing risk-based compliance processes.

As the reforms move from legislation to implementation, and as practical guidance and industry experience develop, we will continue to revisit these topics and share further insights relevant to professional practice.

This article is general information only and should not be treated as legal advice. Law and Accounting practices that are unsure whether they fall within the remit of the AML/CTF Act may need to obtain independent advice.

 Important Resources:

Check if you may be regulated | AUSTRAC

Accounting program starter kit: Getting started | AUSTRAC

Legal profession program starter kit | AUSTRAC

https://www.lawsociety.com.au/understanding-designated-services-when-legal-services-trigger-tranche-2-amlctf-obligations

ABC Listen Radio Segment

CONTACT US

Continue reading

The Budget Fallout and What It Means for SMBs

By Timothy Pope, Senior Manager

This was quite a significant budget, as confirmed by the long-tail media coverage we’ve seen over the past few weeks.

From an insolvency and restructuring perspective, it’s clear that the budget was intended to support long-term reform objectives, but there’s concern about the short- to medium-term stress it may create for already fragile businesses and leveraged investors.

The budget clearly signals a shift away from supporting passive asset inflation and toward productivity, tax integrity and housing supply reform, or at least it’s certainly trying to. Whether that eventuates, we will have to wait and see.

The measures around negative gearing, CGT changes, discretionary trust taxation and broader anti-avoidance settings are significant structural reforms rather than just responses to recent cyclical economic measures.

From a restructuring perspective, that matters because Australian SMBs are deeply intertwined with discretionary trust structures, property-backed borrowing, leveraged investment strategies and intergenerational asset ownership models.

The proposed 30% minimum tax on discretionary trusts alone could trigger a major wave of restructuring activity over the next several years.

Whether that restructuring is informal or formal remains to be seen, but businesses will reassess entity structures, succession planning, and tax efficiency. Trust lawyers will certainly benefit greatly over the next few years!

Overall, it’s an economically ambitious, politically bold budget, and potentially destabilising for marginal businesses already under financial pressure.

Businesses Were Already Under Pressure

One of the biggest issues is that many businesses were already operating with weakened balance sheets before the budget landed.

Higher interest rates, compressed margins, reduced consumer spending and rising ATO arrears are all creating pressure across the SMB market.

Insolvency statistics probably aren’t yet fully capturing the underlying stress.

Many businesses are surviving through delayed creditor payments, invoice financing, funding from directors or related parties, and simply accumulating tax debt.

There’s also been a softening in asset values. During COVID, businesses couldn’t get cars or heavy machinery, so second-hand markets were extremely strong. That environment has changed significantly.

The Sectors Most Exposed

Construction, transport, hospitality and retail remain the sectors most exposed.

In construction, businesses are still dealing with fixed-price contracts signed during peak inflation, alongside labour shortages, fluctuating material costs and project delays.

One subbie goes down, or the project developer goes down, and the domino effect to other parties involved in the project can be significant.

Hospitality and retail businesses continue to feel the impact of reduced discretionary spending. People are staying at home and bunkering down whilst we ride these interest rate rises.

Transport and logistics businesses are also heavily exposed, particularly to fuel supply disruptions and broader economic slowdowns that are impacting freight demand.

If the temporary fuel excise reduction is not extended, and petrol & diesel prices go back up, transport and logistics are going to feel it.

Has the Budget Done Enough?

It’s not all doom and gloom.

There were some positive measures for small businesses in the budget, although they haven’t had the headlines that CGT and negative gearing reform received.

These included:

  • the permanent $20,000 instant asset write-off
  • expanded loss carry-back provisions
  • startup loss refundability
  • more flexibility around PAYG reporting and payments
  • venture capital incentives

Those reforms should improve cash flow flexibility and restructuring options for viable businesses.

But at the same time, broader tax changes reduce investor confidence, property market liquidity, refinancing flexibility and access to private capital.

That combination can materially affect distressed businesses because Australian SMBs often rely on property equity, trust distributions, related-party lending and investor appetite to survive downturns.

What Accountants Should Be Looking At

With the May tax return deadlines now passed, this is a good time for accountants to conduct a thorough financial health check on clients’ businesses.

It’s a good time of the year to assess how businesses are looking.

Areas worth paying closer attention to include:

  • ATO debt positions
  • PAYG flexibility changes
  • payday super obligations
  • fuel-related support measures
  • equipment finance arrangements

One practical issue many businesses overlook is equipment finance consolidation. Many businesses have equipment leased from multiple financiers and lenders, and consolidating those arrangements can sometimes improve cash flow and simplify repayments.

ATO Enforcement Pressure Is Rising

One of the biggest concerns moving forward is the increasing enforcement activity coming from the ATO.

Director penalty notices, garnishee notices and winding-up applications are all increasing, with directors increasingly being pursued personally for unpaid GST, PAYG withholding and superannuation liabilities.

There’s no meaningful relief from the ATO’s enforcement pressure.

Over the next two to three years, there will likely be:

  • increased insolvency events
  • more restructuring activity
  • Higher voluntary administration volumes
  • increased creditor enforcement

The trust restructuring measures will also create legal and transactional complexity that many SMBs simply aren’t prepared for.

Ultimately, the budget feels like a long-term play and an attempt to correct broader structural issues in the economy. For many SMBs already operating under pressure, the short-term fallout could be significant, so having trusted advisors in their corner will be a critical future-proofing strategy.

CONTACT US

Continue reading